Exposing the Libyan Agenda: A Closer Look at Hillary’s Emails

hilary_clinton_laughs_gaddafi_

By Ellen Brown

Source: Web of Debt

Critics have long questioned why violent intervention was necessary in Libya. Hillary Clinton’s recently published emails confirm that it was less about protecting the people from a dictator than about money, banking, and preventing African economic sovereignty.

The brief visit of then-Secretary of State Hillary Clinton to Libya in October 2011 was referred to by the media as a “victory lap.” “We came, we saw, he died!” she crowed in a CBS video interview on hearing of the capture and brutal murder of Libyan leader Muammar el-Qaddafi.

But the victory lap, write Scott Shane and Jo Becker in the New York Times, was premature. Libya was relegated to the back burner by the State Department, “as the country dissolved into chaos, leading to a civil war that would destabilize the region, fueling the refugee crisis in Europe and allowing the Islamic State to establish a Libyan haven that the United States is now desperately trying to contain.”

US-NATO intervention was allegedly undertaken on humanitarian grounds, after reports of mass atrocities; but human rights organizations questioned the claims after finding a lack of evidence. Today, however, verifiable atrocities are occurring. As Dan Kovalik wrote in the Huffington Post, “the human rights situation in Libya is a disaster, as ‘thousands of detainees [including children] languish in prisons without proper judicial review,’ and ‘kidnappings and targeted killings are rampant’.”

Before 2011, Libya had achieved economic independence, with its own water, its own food, its own oil, its own money, and its own state-owned bank. It had arisen under Qaddafi from one of the poorest of countries to the richest in Africa. Education and medical treatment were free; having a home was considered a human right; and Libyans participated in an original system of local democracy. The country boasted the world’s largest irrigation system, the Great Man-made River project, which brought water from the desert to the cities and coastal areas; and Qaddafi was embarking on a program to spread this model throughout Africa.

But that was before US-NATO forces bombed the irrigation system and wreaked havoc on the country. Today the situation is so dire that President Obama has asked his advisors to draw up options including a new military front in Libya, and the Defense Department is reportedly standing ready with “the full spectrum of military operations required.”

The Secretary of State’s victory lap was indeed premature, if what we’re talking about is the officially stated goal of humanitarian intervention. But her newly-released emails reveal another agenda behind the Libyan war; and this one, it seems, was achieved.

Mission Accomplished?

Of the 3,000 emails released from Hillary Clinton’s private email server in late December 2015, nearly a third were from her close confidante Sidney Blumenthal, the Clinton aide who gained notoriety when he testified against Monica Lewinsky. One of these emails, dated April 2, 2011, reads in part:

Qaddafi’s government holds 143 tons of gold, and a similar amount in silver . . . . This gold was accumulated prior to the current rebellion and was intended to be used to establish a pan-African currency based on the Libyan golden Dinar. This plan was designed to provide the Francophone African Countries with an alternative to the French franc (CFA).

In a “source comment,” the original declassified email adds:

According to knowledgeable individuals this quantity of gold and silver is valued at more than $7 billion. French intelligence officers discovered this plan shortly after the current rebellion began, and this was one of the factors that influenced President Nicolas Sarkozy’s decision to commit France to the attack on Libya. According to these individuals Sarkozy’s plans are driven by the following issues:

  1. A desire to gain a greater share of Libya oil production,
  2. Increase French influence in North Africa,
  3. Improve his internal political situation in France,
  4. Provide the French military with an opportunity to reassert its position in the world,
  5. Address the concern of his advisors over Qaddafi’s long term plans to supplant France as the dominant power in Francophone Africa

Conspicuously absent is any mention of humanitarian concerns. The objectives are money, power and oil.

Other explosive confirmations in the newly-published emails are detailed by investigative journalist Robert Parry. They include admissions of rebel war crimes, of special ops trainers inside Libya from nearly the start of protests, and of Al Qaeda embedded in the US-backed opposition. Key propaganda themes for violent intervention are acknowledged to be mere rumors. Parry suggests they may have originated with Blumenthal himself. They include the bizarre claim that Qaddafi had a “rape policy” involving passing Viagra out to his troops, a charge later raised by UN Ambassador Susan Rice in a UN presentation. Parry asks rhetorically:

So do you think it would it be easier for the Obama administration to rally American support behind this “regime change” by explaining how the French wanted to steal Libya’s wealth and maintain French neocolonial influence over Africa – or would Americans respond better to propaganda themes about Gaddafi passing out Viagra to his troops so they could rape more women while his snipers targeted innocent children? Bingo!

Toppling the Global Financial Scheme

Qaddafi’s threatened attempt to establish an independent African currency was not taken lightly by Western interests. In 2011, Sarkozy reportedly called the Libyan leader a threat to the financial security of the world. How could this tiny country of six million people pose such a threat? First some background.

It is banks, not governments, that create most of the money in Western economies, as the Bank of England recently acknowledged. This has been going on for centuries, through the process called “fractional reserve” lending. Originally, the reserves were in gold.  In 1933, President Franklin Roosevelt replaced gold domestically with central bank-created reserves, but gold remained the reserve currency internationally.

In 1944, the International Monetary Fund and the World Bank were created in Bretton Woods, New Hampshire, to unify this bank-created money system globally. An IMF ruling said that no paper money could have gold backing. A money supply created privately as debt at interest requires a continual supply of debtors; and over the next half century, most developing countries wound up in debt to the IMF. The loans came with strings attached, including “structural adjustment” policies involving austerity measures and privatization of public assets.

After 1944, the US dollar traded interchangeably with gold as global reserve currency. When the US was no longer able to maintain the dollar’s gold backing, in the 1970s it made a deal with OPEC to “back” the dollar with oil, creating the “petro-dollar.”  Oil would be sold only in US dollars, which would be deposited in Wall Street and other international banks.

In 2001, dissatisfied with the shrinking value of the dollars that OPEC was getting for its oil, Iraq’s Saddam Hussein broke the pact and sold oil in euros. Regime change swiftly followed, accompanied by widespread destruction of the country.

In Libya, Qaddafi also broke the pact; but he did more than just sell his oil in another currency.

As these developments are detailed by blogger Denise Rhyne:

For decades, Libya and other African countries had been attempting to create a pan-African gold standard.  Libya’s al-Qadhafi and other heads of African States had wanted an independent, pan-African, “hard currency.”

Under al-Qadhafi’s leadership, African nations had convened at least twice for monetary unification.  The countries discussed the possibility of using the Libyan dinar and the silver dirham as the only possible money to buy African oil.

Until the recent US/NATO invasion, the gold dinar was issued by the Central Bank of Libya (CBL).  The Libyan bank was 100% state owned and independent.  Foreigners had to go through the CBL to do business with Libya.  The Central Bank of Libya issued the dinar, using the country’s 143.8 tons of gold.

Libya’s Qadhafi (African Union 2009 Chair) conceived and financed a plan to unify the sovereign States of Africa with one gold currency (United States of Africa).  In 2004, a pan-African Parliament (53 nations) laid plans for the African Economic Community – with a single gold currency by 2023.

African oil-producing nations were planning to abandon the petro-dollar, and demand gold payment for oil/gas.

Showing What Is Possible

Qaddafi had done more than organize an African monetary coup. He had demonstrated that financial independence could be achieved. His greatest infrastructure project, the Great Man-made River, was turning arid regions into a breadbasket for Libya; and the $33 billion project was being funded interest-free without foreign debt, through Libya’s own state-owned bank.

That could explain why this critical piece of infrastructure was destroyed in 2011. NATO not only bombed the pipeline but finished off the project by bombing the factory producing the pipes necessary to repair it. Crippling a civilian irrigation system serving up to 70% of the population hardly looks like humanitarian intervention. Rather, as Canadian Professor Maximilian Forte put it in his heavily researched book Slouching Towards Sirte: NATO’s War on Libya and Africa:

[T]he goal of US military intervention was to disrupt an emerging pattern of independence and a network of collaboration within Africa that would facilitate increased African self-reliance. This is at odds with the geostrategic and political economic ambitions of extra-continental European powers, namely the US.

Mystery Solved

Hillary Clinton’s emails shed light on another enigma remarked on by early commentators. Why, within weeks of initiating fighting, did the rebels set up their own central bank? Robert Wenzel wrote in The Economic Policy Journal in 2011:

This suggests we have a bit more than a rag tag bunch of rebels running around and that there are some pretty sophisticated influences. I have never before heard of a central bank being created in just a matter of weeks out of a popular uprising.

It was all highly suspicious, but as Alex Newman concluded in a November 2011 article:

Whether salvaging central banking and the corrupt global monetary system were truly among the reasons for Gadhafi’s overthrow . . . may never be known for certain – at least not publicly.

There the matter would have remained – suspicious but unverified like so many stories of fraud and corruption – but for the publication of Hillary Clinton’s emails after an FBI probe. They add substantial weight to Newman’s suspicions: violent intervention was not chiefly about the security of the people. It was about the security of global banking, money and oil.

Errata: Sidney Blumenthal is not an attorney, as originally stated in this article. When he earned notoriety as Bill Clinton’s defender against Monica Lewinsky, it was as special adviser for the Clintons.

__________________

Ellen Brown is an attorney and author of twelve books, including the best-selling Web of Debt. Her latest book, The Public Bank Solution, explores successful public banking models historically and globally. Her 300+ blog articles are at EllenBrown.com. Listen to “It’s Our Money with Ellen Brown” on PRN.FM.


Related Podcast:  Progressive Commentary Hour – 03.15.16 James and Joanne Moriarty on the real motives behind the 2011 invasion of Libya.

The Clock Inside Us

time-travel_2

By Eman Shahata

Source: The New Inquiry

Once a weapon to combat idleness, the clock has become a prosthesis, augmenting the human body to override its need for rest

IF time is money, then sleep is theft. Today’s cult of busyness regards sleep as a defect that threatens to render people competitively unfit. In a recent article for the Guardian, Lucy Rock wrote about CEOs’ “competitive sleep deprivation,” with top executives sleeping for a mere three to four hours, mimicking Margaret Thatcher’s four-hour sleep cycle when she was in office. Similarly, Angela Ahrendts, head of retail at Apple and former CEO of Burberry, has claimed she “gets a headache when she sleeps for more than six hours.”

Such enthusiasm for sleeplessness seems to make an executive virtue out of a capitalistic necessity. But it has deep epistemological roots. In the wake of Enlightenment and in tandem with the emergence of capitalism, humans began to view nature as a pool of resources to be tamed, mastered, owned, and directed toward fulfilling human desires. It wasn’t long before this conquest of nature was redirected toward the intransigencies of human nature. Despite all the technological advances that positivistic science yielded, humans were still faced with their own physical limitations. They could build skyscrapers of glass and steel that defied gravity in the name of human reason, yet they could not tame the unreasonable demands of their own body for rest.

The attempt to tame the body of its unprofitable tendency to tire began as an effort to make “saving time” a moral issue. Sixteenth-century moralist and mercantilist discourses already regarded punctuality as a prerequisite for the conception of a modern man, the pinnacle of social development in an imagined context of linear progress. British historian E.P. Thompson points out in “Time, Work-Discipline and Industrial Capitalism” that toward the end of the 17th century, as wage labor relations began to become more prevalent, time began to be conceived as a precious commodity to be spent rather than merely passed. “Those who are employed experience a distinction between their employer’s time and their ‘own’ time,” Thompson notes. “And the employer must use the time of his labor, and see that it is not wasted.” Tolling bells and fines levied by employers taught students and workers that their time was being counted, that it was a regulated and regimented currency.

Moralists urged “time thrift,” and framed the waste of time as summoning divine punishment. As British nonconformist minister Oliver Heywood put it in the 17th century tract Meetness for Heaven, “This is our working day, our market time … O Sirs, sleep now, and awake in hell, whence there is no redemption.” Paternalist and colonialist discourses, whether in addressing the English poor or indigenous people from developing countries, represented idleness as a trait of those who are “naturally inferior.” For instance, as Thompson notes, clergyman John Clayton’s pamphlet “Friendly Advice to the Poor” urges the factory worker, whom he refers to as a “sluggard,” to use his time efficiently and refrain from “dulling his spirit by Indolence.” Similarly, where theories of social evolutionism gained prominence, time discipline was seen as essential for the transition to “mature societies.” Thompson notes how economic-growth theorists viewed Mexican mineworkers as “indolent and childlike people” because of their deficient time discipline.

Parallel to the rise of “time thrift” comes the monumental role of the clock. In 17th century Britain, clocks restructured work habits by materializing the ethic of time thrift, setting a clear demarcation between “work” and “life” and reminding workers of their tasks. The omnipresence of clocks was a guarantor of regulation, it ensured the institution of order in the workspace. The clock’s ubiquity legitimized time discipline and naturalized it, making it banal and commonsensical. It made sure that no one escaped the tempo.

One might say that the clock becomes a subject, with agency in its own right, shaping social customs and subjecting people to its rhythms. As anthropologist Bruno Latour has argued, technology and things are not simply animated by humans but also mediate human action. And as anthropologist Benjamin Snyder argues, clocks served the purpose of training and manipulating the body to accomplish set tasks, thereby “turning it into an inexhaustible source of energy.” The incessant sound of the ticking clock, the mounting anxiety it almost automatically evokes, has come to regulate the body and embed it within the culture of busyness.

If clocks are agents that shape human actions, is it valid to assume that clocks are an “other”? By making sure everyone maximizes their efficiency, clocks address the physical limitations of the human body, becoming a kind of prosthesis that pushes humans closer to reaching an “optimal” state of activity.

This is reflected in the late 19th century emergence of the idea of an “internal clock,” which exemplifies how biological processes can be redefined in terms of prominent material objects. By this means, the ideology of time discipline— inseparable from the clock—becomes seen as a natural imperative. In the wake of the clock’s ubiquity, positivist and scientific rhetoric began to depict the biological clock as an “endogenous” factor that operates according to “innate” biological rhythms, leading to medical advice shaped by the metaphors it employs: “how to reset your internal clock” and so on. Such advice points to the mechanization of the body, which now requires “daily maintenance.”

It may seem as if the presence of a master clock in our brains, which synchronizes and sets sleeping patterns on its own, means we no longer need an outside force to tame our bodies. Our bodies have internalized this systemic regulation, becoming in this sense, machinic. However, what implications arise from this? This mechanization of the body—a precursor and template for the ongoing reconceptualization of the self in terms of quantities alone—reflects how our bodies have become products, rather than agents, of a culture of busyness and rationality that glorifies productivity. Scientific discourses have succeeded in masking the way we’ve been clocked in and can no longer clock out. 

Saturday Matinee: Hemp Doc Double Feature

MV5BMjE4ODY2OTI5N15BMl5BanBnXkFtZTcwNTk0OTcxMQ@@._V1_SX214_AL_MV5BMjA3Mzk5NDQ1OV5BMl5BanBnXkFtZTcwOTQwMjIyMQ@@._V1_SX214_AL_The Hemp Revolution (1995) covers the history, cultivation and usage of hemp including food, fuel, building material and medicine. It also explores some of the factors behind the prohibition of hemp production in the U.S. in 1938 (including pressure from the petro-chemical industry). The impressive roster of interview subjects featured in the film includes such notable figures as Dr. Andrew Weil, Dr. Lester Grinspoon, Terence McKenna, Peter Dale Scott, and Prof. Sheri Tonn among many others.
The Emperor of Hemp (1999) documents the life of Jack Herer, his struggle for the decriminalization of cannabis and hemp and his legacy. It’s also an overview of his seminal book The Emperor Wears No Clothes: The Official Hemp Bible including the history and many utilizations of hemp, the conspiracy against it, and a rallying cry to end its prohibition.

Hillary Clinton Breaks the Irony Meter

By Kevin Carson

Source: Center for a Stateless Society

At the March 9 Democratic debate, Hillary Clinton had this to say about competitor Bernie Sanders’s favorable comments on Castro’s Cuba and the Sandinista regime in the ’80s:  “if the values are that you oppress people, you disappear people, imprison people or even kill people for expressing their opinions…, that is not the kind of revolution of values that I ever want to see anywhere.” This, coming from a former Secretary of State who backed a right-wing coup in Honduras and proudly name-drops Henry Kissinger — Henry Kissinger! — as a close friend and mentor, is the kind of thing the Onion can’t compete with.

If Kissinger was known for anything in his years as National Security Adviser and Secretary of State, it was installing dictators who oppressed, disappeared and imprisoned people. He oversaw a wave of coups that swept South America in the late ’60s and ’70s, installing right-wing military regimes that tortured, murdered or disappeared dissidents by the thousands, and where a common fate for labor and peasant activists was to be found in a ditch with their faces hacked off. Under Kissinger the U.S. actively supported Operation Condor — the program by which these South American dictators used torture and murder to suppress opposition — with military aid and technical assistance. He gave the green light to Indonesia’s genocidal invasion of East Timor.

Clinton has a long history of close personal friendship with this monster, and indeed touts herself as something of a protege. According to both Hillary and Bill, Kissinger praised her for running the State Department better than anybody in decades. And well might he praise her, because she’s followed in his footsteps in many ways. As Secretary of State, she oversaw the sale of millions of dollars worth of arms to despotic regimes that oppressed, disappeared and imprisoned people for expressing their opinions — many of which regimes were also large donors to the Clinton Foundation. And while we’re on the subject of people being murdered and disappeared, how about Berta Caceres — an activist murdered by the right-wing Honduran regime whose seizure of power Clinton backed in 2009?

As senator, Clinton voted to authorize George Bush’s criminal war of aggression on Iraq, which has resulted in hundreds of thousands of Iraqi deaths since 2003. She says now it was “a mistake.” It was a mistake all right. She mistakenly believed the vote would make her more viable as a future presidential candidate. She mistakenly predicted the way the political winds would be blowing when she decided to run for president.

And don’t forget Clinton’s support for the Obama administration’s indiscriminate use of drones for extrajudicial killing. Many of the victims were civilians, and hundreds of them were actually children.

If you add it all up, Hillary Clinton still isn’t quite the war criminal her old friend and mentor Henry Kissinger is. Those are some big, bloody shoes to fill. But if she’s elected she’ll grow into them.

A Warning From the B.I.S.: the Calm Before the Storm?

banker-thief

By Mike Whitney

Source: CounterPunch

The Bank for International Settlements (BIS) is worried that recent ructions in the equities markets could be a sign that another financial crisis is brewing. In a sobering report titled “Uneasy calm gives way to turbulence”  the BIS states grimly: “We may not be seeing isolated bolts from the blue but the signs of a gathering storm that has been building for a long time.”

The authors of the report are particularly concerned that the plunge in stock prices and the slowdown in global growth are taking place at the same time that investor confidence in central banks is waning. The Bank Of Japan’s announcement that it planned to introduce negative interest rates (aka–NIRP or negative interest rate policy) in late January illustrates this point. The BOJ hoped that by surprising the market, the policy would have greater impact on borrowing thus generating more growth. But, instead, the announcement set off a “second phase of turbulence” in stock and currency markets as nervous investors sold off risk assets and moved into safe haven bonds. The BOJ’s action was seen by many as act of desperation by a policymaker that is rapidly losing control of the system. According to the BIS:

“Underlying some of the turbulence of the past few months was a growing perception in financial markets that central banks might be running out of effective policy options.”

This is a recurrent theme in the BIS report, the notion that global CBs have already used their most powerful weapons and are currently trying to muddle-by with untested, experimental policies like negative rates that slash bank profitability while having little impact on lending.

While the BIS report provides a good rundown of recent events in the financial markets, it fails to blame central banks for any of the problems for which they alone are responsible. The sluggish performance of the global economy, the massive debt overhang, and the erratic behavior of the stock market are all directly attributable to the cheap money policies coordinated and implemented by central banks following the Great Recession in 2008.  It’s hard to believe that the BIS’s failure to insert this fact into its narrative was purely accidental.

But the real problem with the BIS report is not that it refuses to assign blame for the current condition of the markets and the economy,  but that it deliberately misleads its readers about the facts. While it’s true that China is facing slower growth, oil prices are plunging, emerging markets have been battered by capital flight, and yields on junk bonds are relentlessly rising, it’s also true that central bank policy is not primarily designed to address these problems, but to ensure the continued profitability of its main constituents,  the big banks and mega-corporations. Keep in mind, the global economy has been sputtering for the last 6 years, but the BIS has only expressed alarm just recently.  Why? What’s changed?

What’s changed is profits are down, and when profits are down,  Wall Street and its corporate allies lean on the central banks to work the levers to improve conditions. Here’s more on the so called “earnings recession” from an article in the Wall Street Journal titled “S&P 500 Earnings: Far Worse Than Advertised”:

“There’s a big difference between companies’ advertised performance in 2015 and how they actually did.

How big? ….S&P earnings per share fell by 12.7%, according to S&P Dow Jones Indices. That is the sharpest decline since the financial crisis year of 2008. Plus, the reported earnings were 25% lower than the pro forma figures—the widest difference since 2008 when companies took a record amount of charges.

The implication: Even after a brutal start to 2016, stocks may still be more expensive than they seem. Even worse, investors may be paying for earnings and growth that aren’t anywhere near what they think. The result could be that share prices have even further to fall before they entice true value investors.” ( “S&P 500 Earnings: Far Worse Than Advertised“, Wall Street Journal)

Profits are down and stocks are in trouble. Is it any wonder why the BIS is running around with its hair on fire?

Also, corporate earnings have dropped for two straight quarters which is a sign that the economy is headed for a slump. Take a look at this clip from CNBC:

“Recessions have followed consecutive quarters of earnings declines 81 percent of the time, according to an analysis from JPMorgan Chase strategists, who said they combed through 115 years of records for their findings.”(CNBC)

“81 percent” chance of a recession?

Yep.

This is what the BIS is worried about.  They could are less about China or the instability they’ve created with their zero rates and cheap money policies. Those things simply don’t factor into their decision-making. It’s all just fluff for the sheeple. Here’s more from Jim Quinn at Burning Platform:

“The increasing desperation of corporate CEOs is clear, as accounting gimmicks and attempts to manipulate earnings in 2015 has resulted in the 2nd largest discrepancy between reported results and GAAP results in history, only surpassed in 2008…..Based on fake reported earnings per share, the profits of the S&P 500 mega-corporations were essentially flat between 2014 and 2015…..earnings per share plunged by 12.7%, the largest decline since the memorable year of 2008….

With approximately $270 billion of “one time” add-backs to income used to deceive the public, the true valuation of the median S&P 500 stock is now the highest in history – higher than 1929, 2000, and 2007. Wall Street’s latest con game, with the active participation of corporate CEO co-conspirators, is a last ditch effort to fend off the inevitable stock market crash….All economic indicators are flashing red for recession. Stocks are poised for a 40% decline faster than you can say Wall Street criminal banks.” (“The Great Corporate Earnings Fraud“, Burning Platform)

Get it? When the profitability of the world’s biggest corporations are at stake, the central banks will move heaven and earth to lend a hand. This was the basic subtext of the discussions at the recent G-20 summit in Shanghai, China. The finance ministers and central bankers wracked their brains for two days to see if they could settle on new strategies for boosting earnings. In fact, the austerity-minded IMF even called on the G-20 to support a coordinated plan for fiscal stimulus to  boost activity and decrease the risks to the equities markets. Unfortunately, finance ministers balked because fiscal stimulus puts upward pressure on wages and shifts more wealth to working stiffs. That’s why the idea was shelved, because the oligarchs can’t stand the idea that workers are getting a leg-up. What they want is a workforce that scrapes by on minimum wage and lives in constant fear of losing their job.  The class war continues to be a top priority among the nations voracious CEOs and corporate bigwigs.

The “failed” G-20 summit was clearly a turning point for the markets. Now that the central banks are out of ammo, the only hope to keep stock prices artificially high rested on Keynesian fiscal stimulus injected directly into the real economy. That hope was extinguished at the meetings. The prospect that equities can continue to climb higher in the face of shrinking profits, tighter credit, slower growth and bigger corporate debtloads is unrealistic to say the least. Just check out this excerpt from a recent article at Bloomberg:

“Companies still have a little time before they must pay down the bulk of $9.5 trillion of debt maturing in the next five years….But it’s not getting any easier for these corporations to borrow, at least not in the U.S. In fact, many of these obligations are becoming harder and more expensive to repay at a time when companies face a historic pile of bonds and loans coming due.

It’s not terribly surprising that companies have a bigger debt load to pay down. They borrowed trillions of dollars on the heels of unprecedented stimulus efforts started by the Federal Reserve at the end of 2008 during the worst financial crisis since the Depression. They kept piling on the leverage as central banks around the world doubled down on low-rate policies and kept purchasing assets to encourage investors to buy riskier securities….”(“Scaling the $9.5 trillion debt wall, Bloomberg)

DB-US-Corp-leverage-close-to-peak

What the author is saying is that central bank policy seduced corporations into borrowing tons of money that they frittered-away on stock buybacks and dividends, neither of which create the revenue streams necessary to repay their debts. So rather than build their companies for the future, (Business investment is at record lows) corporations have been behaving the same way the Wall Street banks acted before the Crash of ’08. They’ve been borrowing trillions from Mom and Pop investors via the bond market, goosing their share prices through stock buybacks, increasing executive compensation, and dumping the money in offshore accounts. Now the bill is coming due, and they don’t have the money to repay the debt or the earnings-potential to avoid default. Something’s gotta give.

unnamed

Corporate red ink is one of many reasons why the BIS thinks “We may not be seeing isolated bolts from the blue but the signs of a gathering storm that has been building for a long time.” Like the gigantic asset-price bubble in stocks, it’s a sign that the economy and the markets are headed for a long and painful period of adjustment.


MIKE WHITNEY lives in Washington state. He is a contributor to Hopeless: Barack Obama and the Politics of Illusion (AK Press). Hopeless is also available in a Kindle edition. He can be reached at fergiewhitney@msn.com.


The Federal Reserve and the Global Fracture

Octopus 1912

An Interview with Finnish Journalist Antti J. Ronkainen

Michael Hudson

Source: The Unz Review

Antti J. Ronkainen: The Federal Reserve is the most significant central bank in the world. How does it contribute to the domestic policy of the United States?

Michael Hudson: The Federal Reserve supports the status quo. It would not want to create a crisis before the election. Today it is part of the Democratic Party’s re-election campaign, and its job is to serve Hillary Clinton’s campaign contributors on Wall Street. It is trying to spur recovery by resuming its Bubble Economy subsidy for Wall Street, not by supporting the industrial economy. What the economy needs is a debt writedown, not more debt leveraging such as Quantitative Easing has aimed to promote. But the Fed is in a state of denial that the U.S. and European economies are plagued by debt deflation.

The Fed uses only one policy: influencing interest rates by creating bank reserves at low give-away charges. It enables banks too make easy gains simply by borrowing from it and leaving the money on deposit to earn interest (which has been paid since the 2008 crisis to help subsidize the banks, mainly the largest ones). The effect is to fund the asset markets – bonds, stocks and real estate – not the economy at large. Banks also are heavy arbitrage players in foreign exchange markets. But this doesn’t help the economy recover, any more than the ZIRP (Zero Interest-Rate Policy) since 2001 has done for Japan. Financial markets are the liabilities side of the economy’s balance sheet, not the asset side.

The last thing either U.S. party wants is for the election to focus on this policy failure. The Fed, Treasury and Justice Department will be just as pro-Wall Street under Hillary. There would be no prosecutions of bank fraud, there would be another bank-friendly Attorney General, and a willingness to subsidize banks now that the Dodd-Frank bank reform has been diluted from what it originally promised to be.


So let’s go back to beginning. When the Great Financial Crisis escalated in 2008 the Fed’s response was to lower its main interest rate to nearly zero. Why?

The aim of lowering interest rates was to provide banks with cheap credit. The pretense was that banks might lend to help the economy get going again. But the Fed’s idea was simply to re-inflate the Bubble Economy. It aimed at restoring the value of the mortgages that banks had in their loan portfolios. The hope was that easy credit would spur new mortgage lending to bid housing prices back up – as if this would help the economy rather than simply raising the price of home ownership.

But banks weren’t going to make mortgage loans to a housing market that already was over-lent. Instead, homeowners had to start paying down the mortgages they had taken out. Banks also reduced their credit-card exposure by a few hundred billion dollars. So instead of receiving new credit, the economy was saddled with having to repay debts.

Banks did make money, but not by lending into the “real” production and consumption economy. They mainly engaged in arbitrage and speculation, and lending to hedge funds and companies to buy their own stocks yielding higher dividend returns than the low interest rates that were available.


In addition to the near zero interest rates, the Fed bought US Treasury bonds and mortgage backed securities (MBS) with almost $4 trillion during three rounds of Quantitative Easing stimulus. How have these measures affected the real economy and financial markets?

In 2008 the Federal Reserve had a choice: It could save the economy, or it could save the banks. It might have used a fraction of what became the vast QE credit – for example $1 trillion – to pay off the bad mortgages and write them down. That would have helped save the economy from debt deflation. Instead, the Fed simply wanted to re-inflate the bubble, to save banks from having to suffer losses on their junk mortgages and other bad loans.

Keeping these debts on the books, in full, let banks foreclose on defaulting homeowners. This intensified the debt-deflation, pushing the economy into its present post-2008 depression. The debt overhead is keeping it depressed.

One therefore can speak of a financial war waged by Wall Street against the economy. The Fed is a major weapon in this war. Its constituency is Wall Street. Like the Justice and Treasury Departments, it has been captured and taken hostage.

Federal Reserve chairwoman Janet Yellen’s husband, George Akerlof, has written a good article about looting and fraud as ways to make money. But instead of saying that looting and fraud are bad, the Fed has refused to regulate or move against such activities. It evidently recognizes that looting and fraud are what Wall Street is all about – or at least that the financial system would come crashing down if an attempt were made to clean it up!

So neither the Fed nor the Justice Department or other U.S. Government agencies has sanctioned or arrested a single banker for the trillions of dollars of financial fraud. Just the opposite: The big banks where the fraud was concentrated have been made even larger and more dominant. The effect has been to drive out of business the smaller banks not so involved in derivative bets and other speculation.

The bottom line is that banks made much more by getting Alan Greenspan and the Clinton-Bush Treasury officials to deregulate fraud than they could have made by traditional safe lending. But their gains have increased the economy’s overhead.


Do you believe Mike Whitney’s argument that QE was about a tradeoff between the Fed and the government: the Fed pumped the new bubble and saved the banks that the government didn’t need to bail out more banks. The government’s role was to impose austerity so that inflation and employment didn’t rise – which would have forced the Fed to raise interest rates, ending its QE program? source: http://www.counterpunch.org/2016/01/15/the-chart-that-explains-everything/]

That was a great chart that Mike put up from Richard Koo, and you should reproduce it here. It shows that the Fed’s enormous credit creation had zero effect on raising commodity prices or wages. But stock market prices doubled in just six years, 2008-15, and bond prices rose to new peaks. Banks left much of the QE credit on deposit with the Fed, earning an interest giveaway premium.

(Richard Koo: “The struggle between markets and central banks has only just begun,”

http://www.businessinsider.com/richard-koo-struggle-between-markets-and-central-banks-has-only-just-begun-2015-9?r=UK&IR=T

The important point is that the Fed (backed by the Obama Administration) refused to use this $4 trillion to revive the production-and-consumption economy. It claimed that such a policy would be “inflationary,” by which it meant raising employment and wage levels. The Fed thus accepted the neoliberal junk economics proposing austerity as the answer to any problem – austerity for the industrial economy, not the Fed’s own Wall Street constituency.


According to a Fed staff report, QE would lower the exchange rate of dollar to the other currencies causing competitiveness boost for the U.S. firms. Former finance minister of Brazil Guido Mantega, as well as the chairman of Central Bank of India Raghuram Rajan, have described the Fed’s QE as a “currency war.” What’s your take?

The Fed’s aim was simply to provide banks with low-interest credit. Banks lent to hedge funds to buy securities or make financial bets that yielded more than 0.1 percent. They also lent to companies to buy their own stock, and to corporate raiders for debt-financed mergers and acquisitions. But banks didn’t lend to the economy at large, because it already was “loaned up,” and indeed, overburdened with debt.

Lower interest rates did spur the “carry trade,” as they had done in Japan after 1990. Banks and hedge funds bought foreign bonds paying higher rates. The dollar drifted down as bank arbitrageurs could borrow from the Fed at 0.1 percent to lend to Brazil at 9 percent. Buying these foreign bonds pushed up foreign exchange rates against the dollar. That was a side effect of the Fed’s attempt to help Wall Street make financial gains. It simply didn’t give much consideration to how its QE flooding the global economy with surplus dollars would affect U.S. exports – or foreign countries.

Exchange rate shifts don’t affect export trends as much as textbook models claim. U.S. arms exports to the Near East, and many technology exports are non-competitive. However, a looming problem for most countries is what may happen when ending QE increases the dollar’s exchange rate. If U.S. interest rates go back up, the dollar will strengthen. That would increase the cost to foreign countries of paying dollar-denominated debts. Countries that borrowed all dollars at low interest will need to pay more in their own currencies to service these debts. Imagine what would happen if the Federal Reserve let interest rates rise back to a normal level of 4 or 5 percent. The soaring dollar would push debtor economies toward depression on capital account much more than it would help their exports on trade account.


You have said that QE is fracturing the global economy. What do you mean by that?

Part of the flood of dollar credit is used to buy shares of foreign companies yielding 15 to 20 percent, and foreign bonds. These dollars are turned over to foreign central banks for domestic currency. But central banks are only able to use these dollars to buy U.S. Treasury securities, yielding about 1 percent. When the People’s Bank of China buys U.S. Treasury bonds, it’s financing America’s dual budget and balance-of-payment deficits, both of which stem largely from military encirclement of Eurasia – while letting U.S. investors and the U.S. economy get a free ride.

Instead of buying U.S. Treasury securities, China would prefer to buy American companies, just like U.S. investors are buying Chinese industry. But America’s government won’t permit China even to buy gas station companies. The result is a double standard. Americans feel insecure having Chinese ownership in their companies. It is the same attitude that was directed against Japan in the late 1980s.

I wrote about this financial warfare and America’s free lunch via the dollar standard in Super Imperialism (2002) and The Bubble and Beyond (2012), and about how today’s New Cold War is being waged financially in Killing the Host (2015).


The Democrats loudly criticized the Bush administration’s $700 billion TARP-program, but backed the Fed’s QE purchases worth of almost $4 trillion during the Obama administration. How does this relate to the fact that officially, QE purchases were intended to support economic recovery?

I think you’ve got the history wrong. My Killing the Host describes how the Democrats supported TARP, while the Republican Congress opposed it on populist grounds. Republican Treasury Secretary Hank Paulson offered to use some of the money to aid over-indebted homeowners, but President-elect Obama blocked that – and then appointed Tim Geithner as Treasury Secretary. FDIC head Sheila Bair and by SIGTARP head Neil Barofsky have written good books about Geithner’s support for Wall Street (and especially for Citigroup and Goldman Sachs) against the interests of the economy at large.

If you are going to serve Wall Street – your major campaign contributors – you are going to need a cover story pretending that this will help the economy. Politicians start with “Column A”: their agenda to reimburse their campaign contributors – Wall Street and other special interests. Their public relations team and speechwriters then draw up “Column B”: what public voters want. To get votes, a rhetorical cover story is crafted. I describe this in my forthcoming J is for Junk Economics, to be published in March. It’s a dictionary of Orwellian doublethink, political and economic euphemisms to turn the vocabulary around and mean the opposite of what actually is meant.


How do TARP and QE relate to the Federal Reserve’s mandate about price stability?

There are two sets of prices: asset prices and commodity prices and wages. By “price stability” the Fed means keeping wages and commodity prices down. Calling depressed wage levels “price stability” diverts attention from the phenomenon of debt deflation – and also from the asset-price inflation that has increased the advantages of the One Percent over the 99 Percent. From 1980 to the present, the Fed has inflated the largest bond rally in history as a result of driving down interest rates from 20 percent in 1980 to nearly zero today, as you have noted.

Chicago School monetarism ignores asset prices. It pretends that when you increase the money supply, this increases consumer prices, commodity prices and wages proportionally. But that’s not what happens. When banks created credit (money), they don’t lend much to people to buy goods and services or for companies to make capital investments to employ more workers. They lend money mainly to transfer ownership of assets already in place. About 80 percent of bank loans are mortgages, and the rest are largely for stocks and bond purchases, including corporate takeovers and stock buybacks or debt-leveraged purchases. The effect is to bid up asset prices, while loading down the economy with debt in the process. This pushes up the break-even cost of doing business, while imposing debt deflation on the economy at large.

Wall Street isn’t so interested in exploiting wage labour by hiring it to produce goods for sale, as was the case under industrial capitalism in its heyday. It makes its gains by riding the wave of asset inflation. Banks also gain by making labour pay more interest, fees and penalties on mortgages, and for student loans, credit cards and auto loans. That’s the postindustrial financial mode of exploiting labor and the overall economy. The Fed’s QE program increases the price at which stocks, bonds and real estate exchange for labour, and also promotes debt leverage throughout the economy.


Why don’t economists distinguish between asset-price and commodity price inflation?

The economics curriculum has been turned into an exercise for students to pretend that a hypothetical parallel universe exists in which the rentier classes are job creators, necessary to help economies recover. The reality is that financial modes of getting rich by debt leveraging creates a Bubble Economy – a Ponzi scheme leading to austerity and shrinking markets, which always ends in a convulsion of bankruptcy.

The explanation for why this is not central to today’s economic theory is that the discipline has been captured by this neoliberal tunnel vision that overlooks the financial sector’s maneuvering to make quick trading profits in stocks, bonds, mortgages and derivatives, not to take the time and effort to develop long-term markets. Rentiers seek to throw a cloak of invisibility around how they make money. They know that if economists don’t measure their wealth and the public does not see it, voters will be less likely to bring pressure to regulate and tax it.

Today’s central economic problem is that inflating asset prices by debt leveraging extracts more interest and financial charges. When the resulting debt deflation ends up hollowing out the economy, creditors try to blame labour, or government spending (except for bailouts and QE to help Wall Street). It is as if debtors are exploiting their creditors.


If there is a new class war, what is the current growth model?

It’s an austerity model, as you can see from the eurozone and from the neoliberal consensus that cites Latvia as a success story rather than a disaster leading to de-industrialization and emigration. In real democracies, if economies polarize like they are doing today, you would expect the 99 Percent to fight back by electing representatives to enact progressive taxation, regulate finance and monopolies, and make public investment to raise wages and living standards. In the 19th century this drive led parliaments to rewrite the tax rules to fall more on landlords and monopolists.

Industrial capitalism plowed profits back into new means of production to expand the economy. But today’s rentier model is based on austerity and privatization. The main way the financial sector always has obtained wealth has been by privatizing it from the public domain by insider dealing and indebting governments.

The ultimate financial business plan also is to lend with an eye to end up with the debtor’s property, from governments to companies and families. In Greece the European Central Bank, European Commission and IMF demanded that if the nation’s elected representatives did not sell off the nation’s ports, land, islands, roads, schools, sewer systems, water systems, television stations and even museums to reimburse the dreaded austerity troika for its bailout of bondholders and bankers, the country would be isolated from Europe and faced with a crash. That forced Greece to capitulate.

What seems at first glance to be democracy has been hijacked by politicians who accept the financial class war ideology that the way for an economy to get rich is by austerity. That means lowering wages, unemployment, and dismantling government by turning the public domain over to the financial sector.

By supporting the banking sector even in its predatory and outright fraudulent behavior, U.S. and European governments are reversing the trajectory along which 19th-century progressive industrial capitalism and socialism were moving. Today’s rentier class is not concerned with long-term tangible investment to earn profits by hiring workers to produce goods. Under finance capitalism, an emerging financial over-class makes money by stripping income and assets from economies driven deeper into debt. Attacking “big government” when it is democratic, the wealthy are all in favor of government when it is oligarchic and serves their interests by rolling back the past two centuries of democratic reforms.


Does the Fed realize global turbulences what its unconventional policies have caused?

Sure. But the Fed has painted itself in a corner: If it raises interest rates, this will cause the stock and bond markets to go down. That would reverse the debt leveraging that has kept these markets up. Higher interest rates also would bankrupt Third World debtors, which will not be able to pay their dollar debts if dollars become more expensive in their currencies.

But if the Fed keeps interest rates low, pension funds and insurance companies will have difficulty making the paper gains that their plans imagined could continue exponentially ad infinitum. So whatever it does, it will destabilize the global economy.


China’s stock market has crashed, western markets are very volatile, and George Soros has said that the current financial environment reminds him of the 2008 crash. Should we be worried?

News reports make it sound as if debt-ridden capitalist economies will face collapse if the socialist countries don’t rescue them from their shrinking domestic markets. I think Soros means that the current financial environment is fragile and highly debt-leveraged, with heavy losses on bad loans, junk bonds and derivatives about to be recognized. Regulators may permit banks to “extend and pretend” that bad loans will turn good someday. But it is clear that most government reports and central bankers are whistling in the dark. Changes in any direction may pull down derivatives. That will cause a break in the chain of payments when losers can’t pay. The break may spread and this time public opinion is more organized against 2008-type bailouts.

The moral is that debts that can’t be paid, won’t be. The question is, how won’t they be paid? By writing down debts, or by foreclosures and distress sell-offs turning the financial class into a ruling oligarchy? That is the political fight being waged today – and as Warren Buffet has said, his billionaire class is winning it.


That’s all for now. Thank you Michael!

David Cronenberg’s Videodrome Was a Technology Prophecy

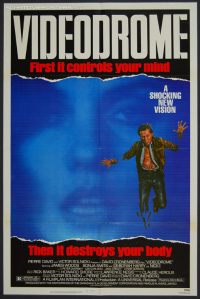
videodrome_one_sheet_movie_poster_l

Editor’s note: Since today marks director David Cronenberg’s 73rd birthday, it’s a good time to appreciate one of his greatest and most notorious works. Though my favorite of his remains the distinctly PKD-like eXistenZ, a close runner up is the cult classic Videodrome, which the following analysis reappraises in the context of contemporary social media-fixated culture.

By Nathan Jurgenson

Source: Omni Reboot

David Cronenberg’s vision of technology as the “new flesh” in Videodrome isn’t so shocking anymore.

Videodrome is the best movie ever made about Facebook.

What felt “vaguely futuristic” about it in 1983 is prescient today: technology and media are ever more intimate, personal, embodied, an interpenetration that David Cronenberg’s film graphically explores.
Videodrome offers a long-needed correction to how we collectively view and talk about technology. As the anti-Matrix, Videodrome understood that media is not some separate space, but something which burrows into mind and flesh. The present has a funny habit of catching up with David Cronenberg.
Still, Videodrome is deeply of its time and place. It’s set in Toronto, where Cronenberg was born and studied at the same time as University of Toronto superstar media theorist Marshall McLuhan, who coined the phrase “the medium is the message.” Beyond McLuhan’s reputation, Toronto was also known as a wired city; among other things, it was an early adopter of cable television.
In suit, Videodrome follows a Toronto cable television president, Max Renn (James Woods). He becomes involved with a radio psychiatrist named Nikki Brand (Debbie Harry, of Blondie fame), who reminds us of popular criticisms of television culture: we want to be stimulated until we’re desensitized, becoming (at best) apolitical zombies and (at worst) amoral monsters. Television signal saturates this film. The satellite dishes, screens, playback devices, and general aesthetics of analogue video are on glorious, geeked-out display. Although Videodrome’s operating metaphor is television, this film can be understood as being a fable about media in general. And what seemed possible with television in 1983 seems obvious today with social media.
Over the course of the film, Max comes to know a “media prophet” named Professor Brian O’Blivion—an obvious homage to Marshall McLuhan. O’Blivion builds a “Cathode Ray Mission,” named after the television set component which shoots electrons and creates images. The Cathode Ray Mission gives the destitute a chance to watch television in order to “patch them back into the world’s mixing board,” akin to McLuhan’s notion of media creating a “global village,” premised on the idea that media and technology, together, form the social fabric. O’Blivion goes on to monologue, “The television screen is the retina of the mind’s eye. Therefore, the television screen is part of the physical structure of the brain. Therefore, whatever appears on the television screen appears as raw experience for those who watch it. Therefore, television is reality; and reality is less than television.”
This is Videodrome’s philosophy. It’s the opposite of The Matrix’s reading of Baudrillard’s theories of simulation, and it goes completely against the common understanding of the Web as “virtual,” of the so-called “offline” as “real.” O’blivion would agree when I claim that “it is wrong to say ‘IRL’ to mean offline: Facebook is real life.”
This logic—that the Web is some other place we visit, a “cyber” space, something “virtual” and hence unreal—is what I call “digital dualism” and I think it’s dead wrong. Instead, we need a far more synthetic understanding of technology and society, media and bodies, physicality and information as perpetually enmeshed and co-determining. If The Matrix is the film of digital dualism, Videodrome is its synthetic and augmented opponent.
As P.J. Rey illustrates, fictional Web-spatiality is the favorite digital dualist plot device. Yet more than fiction books and films, what has come to dominate much of our cultural mythology around the Web is the idea that we are trading “real” communication for something simply mechanical: that real friendship, sex, thinking, and whatever else lazy op-ed writers can imagine are being replaced by merely simulated experiences. The non-coincidental byproduct of inventing the notion of a “cyber” space is the simultaneous invention of “the real,” the “IRL,” the offline space that is more human, deep, and true. Where The Matrix’s green lines of code or Neal Stephenson’s 3D Metaverse may have been the sci-fi milieu of the 1990s, the idea of a natural “offline” world is today’s preferred fiction.
Alternatively, what makes Videodrome, and Cronenberg’s oeuvre in general, so useful for understanding social media is their fundamental assumption that there is nothing “natural” about the body. Cronenberg’s trademark flavor of body-horror is highly posthuman: boundaries are pushed and queered, first through medical technologies in Shivers , Rabid , The Brood , and Scanners , then through media technology in Videodrome  and eXistenZ , then, most notoriously, in The Fly, where the human and animal merge. If The Matrix is René Descartes, Videodrome is Donna Haraway.
Cronenberg’s characters are consistent with Haraway’s theory of the cyborg: not the half-robot with the shifty laser eye, but you and me. In the film, the goal is never to remove the videodrome signal that is augmenting the body, but to reprogram it. To direct it. As Haraway famously wrote, “I’d rather be a cyborg than a goddess.” “Natural” was never a real option anyways.
Max Renn is especially good at finding the real in the so-called “virtual” because he is equally good at seeing virtuality in the “real.” From the beginning, he understands that much of everyday life is a massive media event devoid of meaning. The old flesh is tired, used up, and toxic. The world is filled with a suffering assuaged only by glowing television screens. As the film progresses, the real and unreal blur, making each seem hyperbolic: hallucinations become tangible, while the tangible drips with a surrealism that’s gritty, jumpy, dirty, erotic, and violent—closer to Spring Breakers than The Wizard of Oz. As such, Cronenberg’s universe is always a little sticky: an unease which begs the nightmares to come true, so that we at least know what’s real.
Videodrome’s depiction of techno-body synthesis is, to be sure, intense; Cronenberg has the unusual talent of making violent, disgusting, and erotic things seem even more so. The technology is veiny and lubed. It breaths and moans; after watching the film, I want to cut my phone open just to see if it will bleed. Fittingly, the film was originally titled “Network of Blood,” which is precisely how we should understand social media, as a technology not just of wires and circuits, but of bodies and politics. There’s nothing anti-human about technology: the smartphone that you rub and take to bed is a technology of flesh. Information penetrates the body in increasingly more intimate ways.
This synthesis of the physical and the digital is mirrored in the film’s soundtrack, too. In his book on Videodrome’s production, Tim Lucas calls Howard Shore’s score “bio-electronic” because it was written, programmed into a synthesizer, and played back on a computer in a recording studio while live strings played along. Early in the film, the score is mostly those strings, but as time passes the electronic synthesizers creep up in the mix, forming the bio-electronic synthesis.
The most fitting example of techno-human union in Videodrome is the famous scene of Max inserting his head into a breathing, moaning, begging video screen; somewhere between erotic and hilarious, media and humanity coalesce. There isn’t a person and then an avatar, a real world and then an Internet. They’re merged. As theorists like Katherine Hayles have long taught, technology, society, and the self have always been intertwined. Videodrome knows this, and it shows us with that headfirst dive into the screen—to say nothing of media being inserted directly into a vaginal opening in Max’s stomach, or the gun growing into his hand.

Thirty years after its release, Videodrome remains the most powerful fictional representation of technology-self synthesis. This merger wasn’t invented with the Internet, or even television. Humans and technology have always been co-implicated. We often forget this when talking about the Web, selling ourselves instead a naive picture of defined “virtual” spaces which somehow lack the components of “real” reality. This is why The Matrix and “cyberspace” have long outworn their welcome as a frame for understanding the Internet. It should be of no surprise that body horror is as useful for understanding social media as cyberpunk.