Trust No One

By Michael Krieger

Source: Liberty Blitzkrieg

The title of today’s post is not meant to be taken literally. I trust plenty of people. I trust friends who’ve demonstrated their trustworthiness over the years. I trust my family. Having people in my life I love and trust makes everything far more meaningful and pleasant. I hope people reading this likewise have a circle of trust they’ve built over the years.

On the other hand, you should never trust anyone or anything that hasn’t given you good reason to do so, and if someone or something gives you good reason not to trust them, you should never forget that. The more power a person or institution has in society, the less trustworthy they tend to be. I don’t say this because it’s fun to be cynical, I say this because my life experience has demonstrated its accuracy.

In the 21st century alone, I’ve been given good reason to distrust all sorts of things around me, including the U.S. government (all governments really), intelligence agencies, politicians, mass media, Wall Street and Silicon Valley, to name a few. These power centers make up “society” as we know it in 2020, which is really just massive concentrations of lawless financial and political power obfuscating rampant criminality behind the cover of various ostensibly venerable institutions. What’s most remarkable is how many people still maintain trust in so many of these provably untrustworthy organizations and industries, which speaks to the power of propaganda as well as the comfort of denial.

That said, the ground is clearly beginning to shift on this front. As more and more people recognize that the system’s designed to work against them, increased numbers will reject conventional wisdom and search for an alternative framework. Unfortunately, this next step can be equally treacherous and it’s important not to jump from the frying pan into the fire.

This is where social media comes into play. It offers an endless array of opinions and analysis that you don’t get from mass media, but it’s also filled with bad actors, professional propagandists and con artists. At this point, everyone knows that social media is the new information battleground, so every character or institution with malicious intent is aggressively playing in this arena and often with boatloads of money. The charlatans at MSNBC will have you believe it’s just the Russians or Chinese, but every government and every single special interest on the planet is now involved. They’re all on social media in one form or another, trying to push you in a specific direction that’s usually not in your best interests.

It took me a while, but I’ve finally recognized how unthoughtful and treacherous social media is whenever some big news event hits. Important arguments quickly lose all nuance and devolve into binary talking points and agendas. People split into teams in a way that feels very much akin to the traditional, and now largely discredited, red/blue political theater. For covid-19, it felt like half of Twitter thought it was an extinction-level event, while the other half was convinced the whole thing was a hoax. In the aftermath of George Floyd, you were either cheering on the civil unrest, or wanted to send in the military. Increasingly, if you aren’t in one of two manufactured camps on any issue you’ll be shouted down and ostracized.  That’s not the kind of discussion I’m here for.

As someone who’s found great value in Twitter over the years, I’ve become far more careful in how I use it and where to direct my attention and energy. It reminds me of Mos Eisley in Star Wars, a wretched hive of scum and villainy, but simultaneously a place you can connect with Han Solo and get a spaceship.

As we move forward, it’s going to feel like the world’s ending, and in some ways it will be. No the world isn’t literally ending, but a specific kind of world is ending, and it’ll be extremely difficult for many people to tell the difference as it’s happening. This will likely lead to many more episodes of mass insanity as professional manipulators take advantage of millions upon millions of disoriented people. Priority number one should be to stand guard at the gate of your mind during this time so as not to become a victim.

The best thing you can do from here on out is use your time and energy as productively as possible. We’re going to need builders, creators and inventors more than ever before, because we’re past the point of putting this thing back together. We’ll need to recreate, reimagine and rebuild, and all of this must spring from a point of consciousness in order to bring forth something that is both better and sustainable. Become more beautiful and resilient as others become ugly and unhinged. Focus on what’s within your capacity to control and always remember to resist the crazy.

Saturday Matinee: The Monkey King

“The Monkey King” (2014) is a Hong Kong/Chinese fantasy film directed by Cheang Pou-soi and based on an episode of Journey to the West, a Chinese literary classic written in the Ming Dynasty by Wu Cheng’en. The film focuses on the origin of Sun Wukong (Donnie Yen), the titular protagonist who’s the only one who can prevent the Bull Demon King (Aaron Kwok) from taking over the heavenly kingdom.

The financialization of the end of the world

By Kurt Cobb

Source: resilience

For those who are fans of cartoons from The New Yorker magazine and consistent readers of this blog, you might be able to guess my two favorite cartoons. In the first one, a man in a coat and tie stands at a podium and tells his unseen audience the following: “And so, while the end-of-the-world scenario will be rife with unimaginable horrors, we believe that the pre-end period will be filled with unprecedented opportunities for profit.”

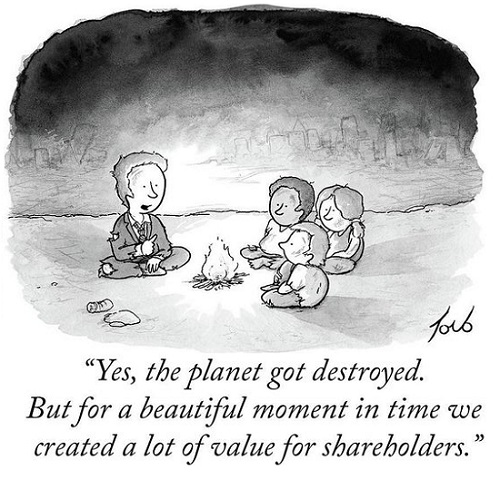
In the second, a man in a tattered suit sits cross-legged near a campfire with three children listening to him intently as he says this: “Yes, the planet got destroyed. But for a beautiful moment in time we created a lot of value for shareholders.”

Now, in the you-can’t-make-this-stuff-up category, financial writer Paul Farrell used the caption from the first cartoon in a 2015 piece for MarketWatch entitled: “Your No. 1 end-of-the-world investing strategy.” The subheading is: “How to pick stocks for the near term when long-term trends say collapse is near.” The subhead actually seems like it might be another caption from a New Yorker cartoon (or possibly one from The Onion). Why exactly would you invest in stocks—as opposed to seeds of food crops and sturdy garden implements—”when long-term trends say collapse is near”? But I’ll put that down to bad headline writing.

In Farrell’s defense, he frequently used his column in MarketWatch to warn his readers of the coming collapse of modern civilization if we don’t change our ways. He was obliged to give investment advice, of course, because that’s what the column was for.

Few other investment gurus are as intellectually honest as Farrell. Among prominent investment managers, only Jeremy Grantham comes close to understanding the scope of the challenges we face. Grantham wrote a piece in 2013 called “The Race of Our Lives” that outlines the myriad challenges humans face. He starts with a discussion of the fall of civilizations. (He updated his views in 2018.)

One would think that the coronavirus pandemic would allow for some sober reflection among those in the financial community as the pandemic-induced crash of the economy and the markets has called into question the stability of practically all the arrangements of modern civilization. Instead, the focus is on how stock markets could be back at or near all-times highs at the beginning of what is arguably the next Great Depression.

The New Yorker cartoons linked above appropriately characterize the madness that grips late-stage civilizations as their pillars begin to fall. Instead of attempting to adapt to new realities, every attempt is made to maintain the current fragile system. The trillions of dollars pumped into the world financial system by central banks and governments in the wake of the pandemic have done little except stoke renewed financial bubbles in practically all financial markets (and thereby bailed out the mostly wealthy owners of financial assets).

The disconnect is hard to miss. The latest reading of the U.S. Federal Reserve Bank of Atlanta’s GDPNow indicator, which is frequently updated as new data becomes available, now predicts that U.S. GDP will contract by 45.5 percent in the current quarter. (The number is annualized and seasonally adjusted.)

Even so the NASDAQ Composite Index hit a new all-time high earlier this month just three months after the recent trough reached during the crash. The S&P 500 is now very close to a new all-time high. Neither development makes sense in the middle of the worst economic downturn since the Great Depression. For comparison, it took more than two years for the NASDAQ Composite from the bottom in 2009 during the Great Financial Crisis to regain its 2007 highs. It took the S&P 500 more than four years.

Of course, the financialization of everything continues. Vaccine makers are in line for government funds. Naturally, it takes money to develop a vaccine. But drug makers aren’t in the business of keeping people healthy. They are in the business of making money. In the United States at least they are helped by the fact that they aren’t liable if their vaccine kills or injuries someone. And, executives in one money-losing pharmaceutical firm cashed in stock right after their company goosed the shares significantly higher with a very preliminary announcement about the company’s coronavirus vaccine research.

When it comes to real estate, it used to be that people bought it for income and as a store of value. Now firms buy real estate mostly with borrowed money and try to make gains mostly through property price appreciation. Often the real estate loans are packaged into securities that are sold and resold as part of the giant Wall Street and worldwide financial casino.

One of the surest signs of the financialization of everything and the growing disconnect of finance from reality is the credit default swap (CDS). The CDS is essentially insurance for loans and bonds. The buyer pays the seller a premium every month. If the instrument insured defaults, the seller provides a predetermined payment to reimburse the CDS buyer. Now here’s the weird thing: An investor doesn’t even have to own the loan or bond to insure it. It’s like me taking out an insurance policy on your home against fire when I have no ownership or interest in the home. In fact, I have every incentive to make sure your house burns down. Do you see any problem with that?

For normal insurance, the buyer must have an insurable interest. Typically, this means the buyer must actually own the thing he or she is insuring. The CDS, on the other hand, is an ideal instrument for those who want to bring on a financial end-of-the-world scenario. The buyers have every reason to want the economy to go down the drain as their payments may be 10 or even 20 times their initial investment.

Many wealthy people fear and even believe an end-of-the-world scenario is possible or probable. Some think they can hold up in luxury bunkers until the dust clears. But what if, when the dust clears, their wealth is gone and the financial world they used to inhabit has vanished.

Perhaps they will sit around campfires telling their grandchildren about the old days when finance was king and the real economy of goods and services was just a place where rubes got their daily bread—while, of course, simultaneously providing an outsized portion to the rich.

Globalists Reveal That The “Great Economic Reset” Is Coming In 2021

By Brandon Smith

Source: Alt-Market.com

For those not familiar with the phrase “global economic reset”, it is one that has been used ever increasingly by elitists in the central banking world for several years. I first heard it referenced by Christine Lagarde, the head of the IMF at the time, in 2014. The reset is often mentioned in the same breath as ideas like “the New Multilateralism” or “the Multipolar World Order” or “the New World Order”. All of these phrases mean essentially the same thing.

The reset is promoted as a solution to the ongoing economic crisis which was triggered in 2008. This same financial crash is still with us today, but now, after a decade of central bank money printing and debt creation, the bubble is even bigger than it was before. As always, the central bank “cure” is far worse than the disease, and the renewed crash we face today is far more deadly than what would have happened in 2008 if we had simply taken our medicine and refused to prop up weak parts of the economy artificially.

Many alternative economists often wrongly attribute the Fed’s habit of making things worse to “hubris” or “ignorance”. They think the Fed actually wants to save the financial system or “protect the golden goose”, but this is not reality. The truth is, the Fed is not a bumbling maintenance man, the Fed is a saboteur, a suicide bomber that is willing to destroy even itself as an institution in order to explode the US economy and clear the path for a new globally centralized one world system. Hence, the “Global Reset”.

In 2015 in my article ‘The Global Economic Reset Has Begun’, I stated:

“The global reset is not a “response” to the process of collapse we are trapped in today. No, the global reset as implemented by central banks and the BIS/IMF is the cause of the collapse. The collapse is a tool, a flamethrower burning a great hole in the forest to make way for the foundations of the globalist Ziggurat to be built….economic disaster serves the interests of elitists.”

Now in 2020 we see the globalist plan coming to fruition, with the elites revealing what appears to be their intent to launch their reset in 2021. The World Economic Forum officially announced the Great Reset initiative as part of their Covid Action Platform last week, and a summit is scheduled in January 2021 to discuss their plans more openly with the world and the mainstream media.

The WEF also posted a rather bizarre video on the Reset, which consists of a series of images of the world falling apart (and images of factories releasing harmless carbon emission into the air which I suppose is meant to scare us with notions of global warming). The destruction is then “reset” at the push of a button, with everything reversing back to a pristine human-less world of nature and the words “Join Us”.

The reset, according to discussions by the IMF, is basically the next stage in the formation of a one-world economic system and potential global government. This seems to fall in line with the solutions offered during the Event 201 pandemic simulation; a simulation of a coronavirus pandemic that was held by the Bill And Melinda Gates Foundation and the World Economic Forum only two months before the REAL THING happened at the beginning of 2020. Event 201 suggested that one of the top solutions to a pandemic would be the institution of a centralized global economic body that could handle the financial response to the coronavirus.

Is it not convenient that the events of the real coronavirus pandemic fall exactly in line with the Event 201 simulation, as well as directly in line with the global reset plans of the IMF and the World Economic Forum? As they say, let no crisis go to waste, or, as is the motto of the globalists “Order Out Of Chaos”.

With civil unrest about to become a way of life for many parts of the world including the US, and the pandemic set for a resurgence of infections after the “reopening”, creating a rationale for a second wave of lockdowns probably in July, the economy as we know it is being destroyed. The last vestiges of the system, hanging by a thin thread after the crash of 2008, are now being cut.

The goal is rather obvious – Terrify the population with poverty, internal conflicts and a broken supply chain until they lobby the establishment for help.  Then, offer the “solution” of medical tyranny, immunity passports, martial law, a global economic system based on a cashless digital society in which privacy in trade is erased, and then slowly but surely form a faceless “multilateral” global government which answers to no one and does whatever it pleases.

I remember back in 2014 when Christine Lagarde first began talking about the reset. That same year she also made a very strange speech to the National Press Club in which she started rambling gleefully about numerology and the “magic number 7”. Many within the club laughed, as there was apparently an inside joke that the rest of us were not privy to. Well, I would point out that the World Economic Forum meeting on the global reset in 2021 will be held exactly 7 years after Lagarde gave that speech. Just another interesting coincidence I suppose…

The new world order, the global reset, is a long running scheme to centralize power, but in a way that is meant to be sustained for centuries to come. The elites know that it is not enough to achieve global governance by force alone; such an attempt would only lead to resistance and eternal rebellion. No, what the elites want is for the public to ASK, even beg for global governance. If the public is tricked into demanding it as a way to save them from the horrors of global chaos, then they are far less likely to rebel against it later. Problem – reaction – solution.

The pandemic is not going away anytime soon. Everyone should expect that state governments and the federal government will call for renewed lockdowns. With these new lockdowns, the US economy in particular will be finished. With 40 million people losing their jobs during the last lockdowns, many states only partially reopened, and only 13% to 18% of small businesses receiving bailout loans to survive, the next two months are going to be a devastating wake-up call.

The real solution will be for people to form more self reliant communities free of the mainstream economy. The real solution should be decentralization and independence, not centralization and slavery. The globalists will seek to interfere with any effort to break from the program. That said, they can do very little if millions of people enact localization efforts at the same time. If people aren’t reliant on the system, then they cannot be controlled by the system.

The real test will come with the final collapse of the existing economy. When stagflation spikes even harder than it is right now and prices of necessities double or triple yet again, and joblessness skyrockets even further, how many people will clamor for the globalist solution and how many will build their own systems? How many will be bowing in submission and how many will be ready to fight back. It is a question I still don’t have an answer to even after 14 years of analysis on the issue.

What I suspect is that many people will fight back. Not as many as we might hope for, but enough to defend the cause of liberty. Maybe this is overly optimistic, but I believe the globalists are destined to lose this war in the long run.

Facebook using “fact-checkers” to censor dissent on Covid19

Familiar tactics of obfuscation and weasel-words deployed to block access to articles

By Off-Guardian.org

Facebook has flagged our article “It’s all bullshit”: 3 links sinking the Covid narrative” as ‘false information’, based on nothing but a single ‘fact check’ website, which does not even claim the information is ‘false’, but merely quibbles over terminologies to justify claiming the information is ‘misleading.’

This is what you see today if you try to access that article on Facebook:

And if you click on the ‘see why’ button you get taken here, to the website of Health Feedback, an “independent fact-checker”.

Of course, they’re not independent – they’re actually funded by Facebook. They are also funded by the “Credibility Coalition”, an NGO focused on “common standards for information credibility”.

The Credibility Coalition are also funded by Facebook. And twitter. And google. And a whole host of unsavoury sounding NGOs.

So, with the idea that “health feedback” are anywhere close to “independent” firmly debunked, let’s see what they have to say.

Firstly, it’s important to note what is actually being “fact-checked” here.

It is not that the three documents were leaked. It is not the accuracy of the quotes used. It is not the statistics cited. In fact, not a single factual claim is being called “false”.

In short, Facebook is well aware that 90% of the article is perfectly provably true.

In fact, it’s not our article they’re allegedly fact-checking, it’s another article in the publication NewsPunch, which relies on one of the same sources we do.

The “fact-check” is entirely devoted to just one of three leaks we describe – the report from German Interior Ministry employee – and even then focuses solely on its provenance rather than its content. In essence, what is being “fact-checked” is not the report itself, but where it came from.

Nowhere in this ‘rebuttal’ does it claim the ‘German Ministry employee’ was lying or making provably false statements. Neither does it challenge the credentials, competence or honesty of the “independent scientists” who co-authored the report.

Instead, it uses diversionary language claiming the document’s main author, Stephan Kohn, was simply sharing his “private opinion” and was not authorised to speak for the government.

The author of the document is Stephan Kohn, a politologist and employee of Germany’s Interior Ministry in the KM 4 department for the Protection of Critical Infrastructures. However, Kohn’s analysis was not requested by the Interior Ministry, as the article claims. On 10 May, Germany’s Interior Ministry issued a press release stating that the employee had disseminated his “private opinion on the corona crisis management” and that the “elaboration was carried out outside the area of responsibility as well as without assignment and authorization”.

This approach should be hauntingly familiar to anyone who has been following the OPCW whistleblower story. Where expert witnesses contradicting the official narrative on Douma were claimed to merely be “disgruntled ex-employees” who were in Syria of their own accord and “never part of the fact-finding mission”.

All these claims have since been shown to be lies.

In addition to these irrelevant obfuscations, the article uses weasel words to construct a flimsy counter-argument:

According to EuroMOMO, the number of excess deaths coinciding with the COVID-19 pandemic was twice the number that occurred during the unusually deadly flu seasons of 2017, 2018, and 2019 (Figure 1).

Note that they only back three years in time, and not all the way to 2000 or 1998, both of which had very similar excess death numbers.

Note also they say “coinciding with”, and not “caused by”. This allows them to cite all the excess deaths in Europe, despite statistics showing that huge numbers of the excess deaths were due to other causes – including the lockdown limiting access to healthcare and increasing poverty.

They are using excess deaths caused by the lockdown, to argue against the accuracy of a report warning that the lockdown will cause excess deaths.

It is going full Orwell. And it is utterly disgusting.

This article simply does not offer any justification for dismissing our article reporting Kohn’s words as ‘false information’. The information is NOT demonstrably false, it is merely contentious, in that the data is open to multiple interpretations.

In fact, the article admits that itself – only able to label the claim as “misleading” or “unsupported”. Nowhere do they use the word “disinformation” or “misinformation” or “false information”. Not once.

And yet that is the label facebook has stuck on it.

Facebook is not suppressing this article because it contains false information at all, it is censoring it because it offers an interpretation of facts that does not support the current mainstream dogma.

This is censorship, pure and simple.

Another Bank Bailout Under Cover of a Virus

By Ellen Brown

Source: Web of Debt

Insolvent Wall Street banks have been quietly bailed out again. Banks made risk-free by the government should be public utilities.  

When the Dodd Frank Act was passed in 2010, President Obama triumphantly declared, “No more bailouts!” But what the Act actually said was that the next time the banks failed, they would be subject to “bail ins” – the funds of their creditors, including their large depositors, would be tapped to cover their bad loans.

Then bail-ins were tried in Europe. The results were disastrous.

Many economists in the US and Europe argued that the next time the banks failed, they should be nationalized – taken over by the government as public utilities. But that opportunity was lost when, in September 2019 and again in March 2020, Wall Street banks were quietly bailed out from a liquidity crisis in the repo market that could otherwise have bankrupted them. There was no bail-in of private funds, no heated congressional debate, and no public vote. It was all done unilaterally by unelected bureaucrats at the Federal Reserve.

“The justification of private profit,” said President Franklin Roosevelt in a 1938 address, “is private risk.” Banking has now been made virtually risk-free, backed by the full faith and credit of the United States and its people. The American people are therefore entitled to share in the benefits and the profits. Banking needs to be made a public utility.

The Risky Business of Borrowing Short to Lend Long

Individual banks can go bankrupt from too many bad loans, but the crises that can trigger system-wide collapse are “liquidity crises.” Banks “borrow short to lend long.” They borrow from their depositors to make long-term loans or investments while promising the depositors that they can come for their money “on demand.” To pull off this sleight of hand, when the depositors and the borrowers want the money at the same time, the banks have to borrow from somewhere else. If they can’t find lenders on short notice, or if the price of borrowing suddenly becomes prohibitive, the result is a “liquidity crisis.”

Before 1933, when the government stepped in with FDIC deposit insurance, bank panics and bank runs were common. When people suspected a bank was in trouble, they would all rush to withdraw their funds at once, exposing the fact that the banks did not have the money they purported to have. During the Great Depression, more than one-third of all private US banks were closed due to bank runs.

But President Franklin D. Roosevelt, who took office in 1933, was skeptical about insuring bank deposits. He warned, “We do not wish to make the United States Government liable for the mistakes and errors of individual banks, and put a premium on unsound banking in the future.” The government had a viable public alternative, a US postal banking system established in 1911. Postal banks became especially popular during the Depression, because they were backed by the US government. But Roosevelt was pressured into signing the 1933 Banking Act, creating the Federal Deposit Insurance Corporation that insured private banks with public funds.

Congress, however, was unwilling to insure more than $5,000 per depositor (about $100,000 today), a sum raised temporarily in 2008 and permanently in 2010 to $250,000. That meant large institutional investors (pension funds, mutual funds, hedge funds, sovereign wealth funds) had nowhere to park the millions of dollars they held between investments. They wanted a place to put their funds that was secure, provided them with some interest, and was liquid like a traditional deposit account, allowing quick withdrawal. They wanted the same “ironclad moneyback guarantee” provided by FDIC deposit insurance, with the ability to get their money back on demand.

It was largely in response to that need that the private repo market evolved. Repo trades, although technically “sales and repurchases” of collateral, are in effect secured short-term loans, usually repayable the next day or in two weeks. Repo replaces the security of deposit insurance with the security of highly liquid collateral, typically Treasury debt or mortgage-backed securities. Although the repo market evolved chiefly to satisfy the needs of the large institutional investors that were its chief lenders, it also served the interests of the banks, since it allowed them to get around the capital requirements imposed by regulators on the conventional banking system. Borrowing from the repo market became so popular that by 2008, it provided half the credit in the country. By 2020, this massive market had a turnover of $1 trillion a day.

Before 2008, banks also borrowed from each other in the fed funds market, allowing the Fed to manipulate interest rates by controlling the fed funds rate. But after 2008, banks were afraid to lend to each other for fear the borrowing banks might be insolvent and might not pay the loans back. Instead the lenders turned to the repo market, where loans were supposedly secured with collateral. The problem was that the collateral could be “rehypothecated,” or used for several loans at once; and by September 2019, the borrower side of the repo market had been taken over by hedge funds, which were notorious for risky rehypothecation. Many large institutional lenders therefore pulled out, driving the cost of borrowing at one point from 2% to 10%.

Rather than letting the banks fail and forcing a bail-in of private creditors’ funds, the Fed quietly stepped in and saved the banks by becoming the “repo lender of last resort.” But the liquidity crunch did not abate, and by March the Fed was making $1 trillion per day available in overnight loans. The central bank was backstopping the whole repo market, including the hedge funds, an untenable situation.

In March 2020, under cover of a national crisis, the Fed therefore flung the doors open to its discount window, where only banks could borrow. Previously, banks were reluctant to apply there because the interest was at a penalty rate and carried a stigma, signaling that the bank must be in distress. But that concern was eliminated when the Fed announced in a March 15 press release that the interest rate had been dropped to 0.25% (virtually zero). The reserve requirement was also eliminated, the capital requirement was relaxed, and all banks in good standing were offered loans of up to 90 days, “renewable on a daily basis.” The loans could be continually rolled over. And while the alleged intent was “to help meet demands for credit from households and businesses at this time,” no strings were attached to this interest-free money. There was no obligation to lend to small businesses, reduce credit card rates, or write down underwater mortgages.

The Fed’s scheme worked, and demand for repo loans plummeted. Even J.P. Morgan Chase, the largest bank in the country, has acknowledged borrowing at the Fed’s discount window for super cheap loans. But the windfall to Wall Street has not been shared with the public. In Canada, some of the biggest banks slashed their credit card interest rates in half, from 21 percent to 11 percent, to help relieve borrowers during the COVID-19 crisis. But US banks have felt no such compunction. US credit card rates dropped in April only by half a percentage point, to 20.15%. The giant Wall Street banks continue to favor their largest clients, doling out CARES Act benefits to them first, emptying the trough before many smaller businesses could drink there.

In 1969, Prime Minister Indira Gandhi nationalized 14 of India’s largest banks, not because they were bankrupt (the usual justification today) but to ensure that credit would be allocated according to planned priorities, including getting banks into rural areas and making cheap financing available to Indian farmers.  Congress could do the same today, but the odds are it won’t. As Sen. Dick Durbin said in 2009, “the banks … are still the most powerful lobby on Capitol Hill. And they frankly own the place.”

Time for the States to Step In

State and local governments could make cheap credit available to their communities, but today they too are second class citizens when it comes to borrowing. Unlike the banks, which can borrow virtually interest-free with no strings attached, states can sell their bonds to the Fed only at market rates of 3% or 4% or more plus a penalty. Why are elected local governments, which are required to serve the public, penalized for shortfalls in their budgets caused by a mandatory shutdown, when private banks that serve private stockholders are not?

States can borrow from the federal unemployment trust fund, as California just did for $348 million, but these loans too must be paid back with interest, and they must be used to cover soaring claims for state unemployment benefits. States remain desperately short of funds to repair holes in their budgets from lost revenues and increased costs due to the shutdown.

States are excellent credit risks – far better than banks would be without the life-support of the federal government. States have a tax base, they aren’t going anywhere, they are legally required to pay their bills, and they are forbidden to file for bankruptcy. Banks are considered better credit risks than states only because their deposits are insured by the federal government and they are gifted with routine bailouts from the Fed, without which they would have collapsed decades ago.

State and local governments with a mandate to serve the public interest deserve to be treated as well as private Wall Street banks that have repeatedly been found guilty of frauds on the public. How can states get parity with the banks? If Congress won’t address that need, states can borrow interest-free at the Fed’s discount window by forming their own publicly-owned banks. For more on that possibility, see my earlier article here.

As Buckminster Fuller said, “You never change things by fighting the existing reality. To change something, create a new model that makes the old model obsolete.” Post-COVID-19, the world will need to explore new models; and publicly-owned banks should be high on the list.
To America, Black Lives Only Sometimes Matter

By Tony Cartalucci

Source: Land Destroyer

There is no doubt that colonialism and racism sit at the root of America’s domestic problems. The push to dominate others abroad is directly linked to the belief that those who are different at home should also be dominated.

There are still Americans alive today that remember segregation laws that denied black Americans their basic rights and dignity. Before that, there was outright slavery.

Even today, racism is still institutionalized. It also permeates American culture, laying just beneath a superficial layer of tolerance and equality.

This is not just about white people who remain racist against blacks and other minorities – a product of America’s terminally ill culture – it is also about fundamental racism that still very much sits at the heart of American foreign and domestic policy – against not only blacks, but virtually every race on the planet from Africans to Asians to even Slavs.

The US is a nation that encourages its people to hate entire groups of people abroad to help justify otherwise unjust wars. Arabs, Chinese people, Russians – are all vilified with bigotry and hatred sanctioned by mainstream American culture. It isn’t hard to see why in a nation like this, hatred for other groups is easily justified in the minds of racists and the unjust.

Not Just Police in America – Racism is a Key Feature of US Foreign Policy 

It was under US President Barack Obama that the US decimated the North African nation of Libya, deposing Libyan leader Muammar Gaddafi – a champion of African dignity and progress and the champion of tens of thousands of blacks from all over Africa who travelled to Libya to find work and a better life – work and a better life Gaddafi provided them until he was brutally murdered and his government replaced by heavily armed, racist terrorists backed by the US and its European allies.

US-backed militants in Libya would hunt down Libya’s black population, killing them, torturing them, and even enslaving them in open air slave markets – a spectacle one might have believed was unthinkable in the 21st century – but something made possible by America, its foreign policy, and its deeply rooted racism and sense of supremacy – despite having a “black” president at the time.

President Obama is hardly the only one to blame – he simply picked up where others left off – and his successor, US President Donald Trump is simply next in line to carry forward systemic US injustice worldwide. The fact that President Obama was black made no difference and simply helps illustrate how while superficial milestones are waved in America’s face – the fundamental rot of injustice, racism, and supremacist thinking persists.

When a nation is able to justify denying one group of people their dignity, worth, and rights as human beings it is a slippery slope that easily leads to other groups likewise being stripped of their humanity and abused.

If Black Lives Matter – They Must Always Matter, Everywhere, All the Time 

Any case of police brutality is tragic and needs to be addressed -a problem in its own right. If officers killed George Floyd because he was black, it represents an additional problem that must also be addressed.

If Americans genuinely believe black lives matter – then they need to commit to fighting injustice against them, and all other victims of American racism and supremacy. If they speak up only when it is popular and “trending” it’s as good as not speaking up at all.

If they are silent when America is mass murdering blacks overseas, killing brown people across the planet, or attempting to normalize racism against Asians – Chinese people in particular – they are complicit in the very sort of deeply rooted, institutionalized racism that underpins US foreign policy and the globe-spanning industrialized injustice it represents – and the very sort of racism that manifests itself as injustice against blacks at home.

America needs genuine opposition to racism. Not opportunistic posturing.

US politicians like Alexandria Ocasio-Cortez pose as dedicated to racial equality and fighting racism – yet she regularly finds herself in support of US military aggression abroad which exclusively targets nations populated by black, brown, and Asian people.

Her most recent display of supreme hypocrisy was her support of US meddling in Hong Kong – an extension of the British Empire’s seizure from and subjugation of this Chinese territory.

The British Empire – of course – also pursued its foreign policy based entirely on the belief that white Westerners were superior to all others and that it was their right – even duty – to impose British “civilization” upon “heathen” races – China was no exception to this belief.

Alexandria Ocasio-Cortez may or may not appreciate that her support for US meddling in Hong Kong helps continue this disgraceful tradition and agenda – believing instead that supporting “democracy” in Hong Kong is not simply the same brand of Anglo-American racism merely repackaged for more sensitive global audiences. But she is supporting racism, supremacy, and hegemony all the same.

Black lives will never matter as long as “Black Lives Matter” remains a hollow political slogan shouted by interests easily able to ignore or even support injustice purveyed by the US against others abroad – including blacks.

Deeply rooted racism in the US is just one of many symptoms of an overall desire for hegemony and the notions of racial, political, and cultural supremacy that underpin it. Until this is addressed, racism will continue, with only the most superficial and unsustainable efforts made to stop it.

As long as America believes it is better than all others abroad – able to justify exploitation, coercion, and even military aggression to assert itself and pursue its “interests” – racism and injustice will persist at home. The same corporate-financier interests driving US injustice abroad see the US population – white and black – as merely another market segment to use and abuse – to divide and conquer – to put under itself for its own benefit.

Black lives matter, whether they are being strangled by a racist white cop in America or being bombed by US warplanes in Libya. Once Americans can unite in both understanding and opposing this across-the-board racism and injustice, something might actually be done about it besides kicking the can down the road for a few more months until the next video of police abuse emerges online.

America will not heal its domestic hatred and divisions if it remains built entirely on projecting and profiting from hatred and division abroad. It was no coincidence that legendary champions for equality like Martin Luther King Jr. were both opposed to racism and injustice at home and ceaselessly opposed  to American aggression and hegemony abroad. The two are linked by the common thread of fundamental injustice. Until they are both exposed and smashed completely, they will both continue.